Business Tax Tip No. 11: Sales and Use Tax Exemptions for Agriculture
Are sales of agricultural equipment exempt from tax?
The sales and use tax does not apply to sales, including rentals, to a farmer of farm equipment used to raise livestock and poultry, prepare, irrigate or tend the soil, or plant, service, harvest, store, clean, dry or transport seeds or crops. Farm equipment that is used for traditional agricultural purposes is exempt from sales and use tax even if attached to real property.
Examples of farm equipment
Balers
Beekeeping equipment
Binders
Blowers
Choppers
Conveyers
Corral Handling Equipment
Cribs
Crushers
Cultipackers
Diggers
Drags
Rollers
Scales
Drills
Dryers
Dusters
Egg handling equipment
Elevators
Farm graders
Farm loaders
Farrowing crates
Feed grinders
Feeders
Forage harvesters
Grain handling equipment
Haybines
Irrigation equipment
Livestock/poultry fans
Milk cans
Milking machines
Milk coolers
Mowers
Poultry equipment
Rollers
Rotary hoes
Seed cleaners
Seeders
Shellers
Sorters
Storage tanks
Sprayers
Subsoilers
Vaccinating panels
What else is included in this exemption?
Both replacement parts and components, including hydraulic oil, are also exempt.
Are there any exemptions for food processing?
Yes. If a farmer is engaged in processing food for sale, there are exemptions available for purchases of capitalized equipment and consumables. These exemptions are explained in Business Tax Tip #9 - Sales and Use Tax Exemptions for Production Activities.
Does the tax apply to sales of livestock?
No. Sales, for agricultural purposes, of livestock, including poultry, are not taxable. Also exempt are sales of feed or bedding for livestock. The raising of horses for breeding purposes is an agricultural purpose, but the maintenance or sale of riding, show or race horses is not. The raising of livestock by members of 4-H or similar organizations for agricultural educational purposes qualifies for tax exemption, but the maintenance and sale of pets, dogs for breeding purposes and animals for testing purposes does not.
Are there any exemptions for agricultural supplies?
Yes. When sold for agricultural purposes, seeds (including plants and seedlings), fertilizer, lime, fungicide, herbicide and insecticide are exempt. These items are exempt when used for raising vegetables at home but are not exempt when used to maintain a flower or other decorative garden or lawn. The tax does not apply to sales of containers used by a farmer to transport farm products to the market or to sales of baler twine or wire. Fuel for use in farm equipment or a farm tractor is also exempt.
Is aquaculture given the same treatment as agriculture?
Yes. Commercial aquaculture and agriculture are treated the same way for sales and use tax purposes.
Are tax numbers needed to claim agricultural exemptions?
No. It is not necessary for purchasers to register with the Comptroller’s Office in order to claim agricultural exemptions.
What records of sales should vendors who sell agricultural equipment and supplies maintain?
When the record of sale does not clearly include all elements necessary to justify exemption, a vendor may ask for a signed statement to indicate that the customer is a farmer or that the purchases will be used only for agricultural purposes. Even if a certification is provided, a vendor must collect the tax, if he or she knows or should know that the purchase does not qualify for exemption.
What kinds of items are not exempt?
Only those items sold under the specific conditions described in this publication are exempt. Sales of hand tools, carpentry, cleaning and maintenance supplies, materials to be incorporated into real property, and materials purchased for personal, rather than agricultural use, are subject to the sales and use tax.
Examples of non-exempt items
Antifreeze
Barbed wire
Brooms
Cement
Clothing
Detergents
Electric drills
Fencing material
General water systems
Hammers
Home appliances
Incinerators
Light bulbs
Lubricants
Motor Oil
Pails
Paint
Paint brushes
Posthole diggers
Pruners
Rakes
Riding lawnmowers
Roofing materials
Sandpaper
Saws Shovels
Snow blowers
Three-wheeled vehicles
Are there any special provisions for sales by farmers?
Yes. The tax does not apply to the sale of an agricultural product by a farmer. However, sales of flowers, sod, decorative trees, shrubs and any other products usually sold by a nursery or horticulturist do not qualify for this exemption.
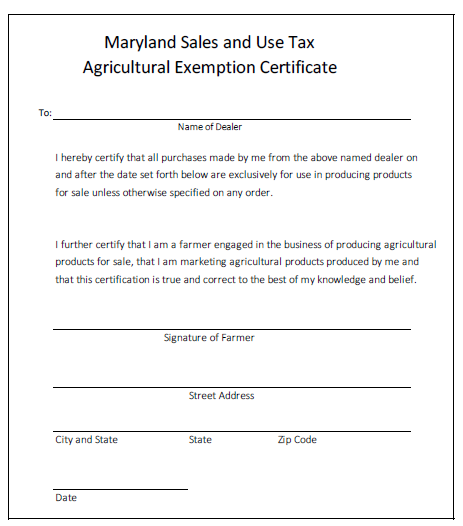 Maryland Sales and Use Tax Agricultural Exemption Certificate